


FIELD NOTES
A friend who works at one of the frontier labs said something to me over drinks the other night:
“I’m long fun, short productivity.”
His argument was basically that the models have already gotten very good at productivity. Coding, research, writing, analysis…all of this gets faster and cheaper from here.
So where does the value go?
Fun, he said. Creativity. Design. Entertainment.
I laughed, but I’ve kept thinking about it.
The velocity of startups right now feels unlike anything I’ve seen before. Companies are being built faster, with fewer people, because increasingly large parts of the work are becoming cheap.
That should create more companies.
It might also make many of them less differentiated (i.e. easier to dupe). Or go for cheaper alternatives even if you’re a happy customer.
If everyone gets access to roughly the same extraordinary productivity, productivity starts to look less like an advantage and more like table stakes.
Maybe that’s why Alexandr Wang’s language around Muse stuck with me this week. His vision is an agent that clears away the planning, emails, calls and logistics until what remains for the human is “the wanting and the dreaming.”
It’s a very Silicon Valley way of describing the future. But it’s also remarkably close to what my friend was saying over drinks.
Humans seem perfectly capable of finding new ways to spend the time technology saves us, e.g. short-form drama apps went from roughly 370 million downloads in Q1 last year to around 850 million this year.
Productivity may become a race toward cheaper execution. Entertainment is a race toward stronger preference.
The supply of things to watch, play and listen to is about to explode. But preference is harder to manufacture.
Desire is scarce. Attention is scarce. Culture is scarce.
That might be the strongest case for being long fun.
-Tara
THE DOWNLOAD
01 — Google prepares to test TPUs in orbit
Google’s Project Suncatcher is about to go into orbit.
On October 1, a refrigerator-sized satellite is scheduled to launch with four of Google’s TPUs. The goal is to test whether the same chips used in terrestrial data centers can survive launch, radiation and the thermal extremes of low Earth orbit.
The idea sounds less absurd when you look at what is happening on Earth. Morgan Stanley now estimates a 30 to 40% gap between projected U.S. data-center power capacity and demand by 2028 (roughly six New York Cities’ worth of baseload electricity).
Suncatcher is Google asking whether some of that compute could eventually go somewhere power is abundant: orbit, with near-continuous sunlight.
The catch is heat. The first prototype can run its TPUs for only about 15 minutes at a time before shutting down so its radiators can catch up.
So this is nowhere near an orbital data center. But AI infrastructure has become constrained enough by power, cooling, land and transmission that putting compute in space has moved from thought experiment to flight hardware.
Why it matters: The search for AI infrastructure is beginning to produce entirely new ideas about where computing should physically live, and what type of computing could actually thrive in space.
02 — Anthropic says Claude found a previously uncharacterized enzyme system
Anthropic has published the first major result from the physical biology lab it revealed earlier this month.
The company gave Claude a broad task: search a massive DNA database for interesting reverse transcriptases. Roughly 950 agents spent 21 hours and 210 million tokens searching more than 200,000 examples before surfacing an unusual system Anthropic calls array-associated reverse transcriptases, or ART.
Scientists then took the hypothesis into the lab and confirmed that part of the system produces distinct short RNAs.
They still don’t know what ART actually does, and the work needs further validation. The reverse transcriptase itself was also not previously unknown.
The interesting part is the loop: hundreds of agents search an enormous hypothesis space, rank the interesting anomalies, and hand a tiny subset to humans for physical experimentation.
Why it matters: AI-driven science is starting to connect large-scale computational search directly to experiments in the real world.
03 — Meta suddenly has a consumer AI stack
Meta is suddently crushing consumer AI.
Their new personal AI agent app Muse has gone from launch to the top of the U.S. app stores in a matter of weeks. Beyond the app, Muse is being pushed into its glasses and other devices, and connected to services across the web like Whatsapp.
Like it’s irresistibly cute Muse charm, a tiny screen-based AI companion that looks like a less creepy Labubu sans teeth and designed to hang from a bag or keychain. It has a screen, fingerprint sensor and real-time voice. Meta says it plans to ship it later this year.
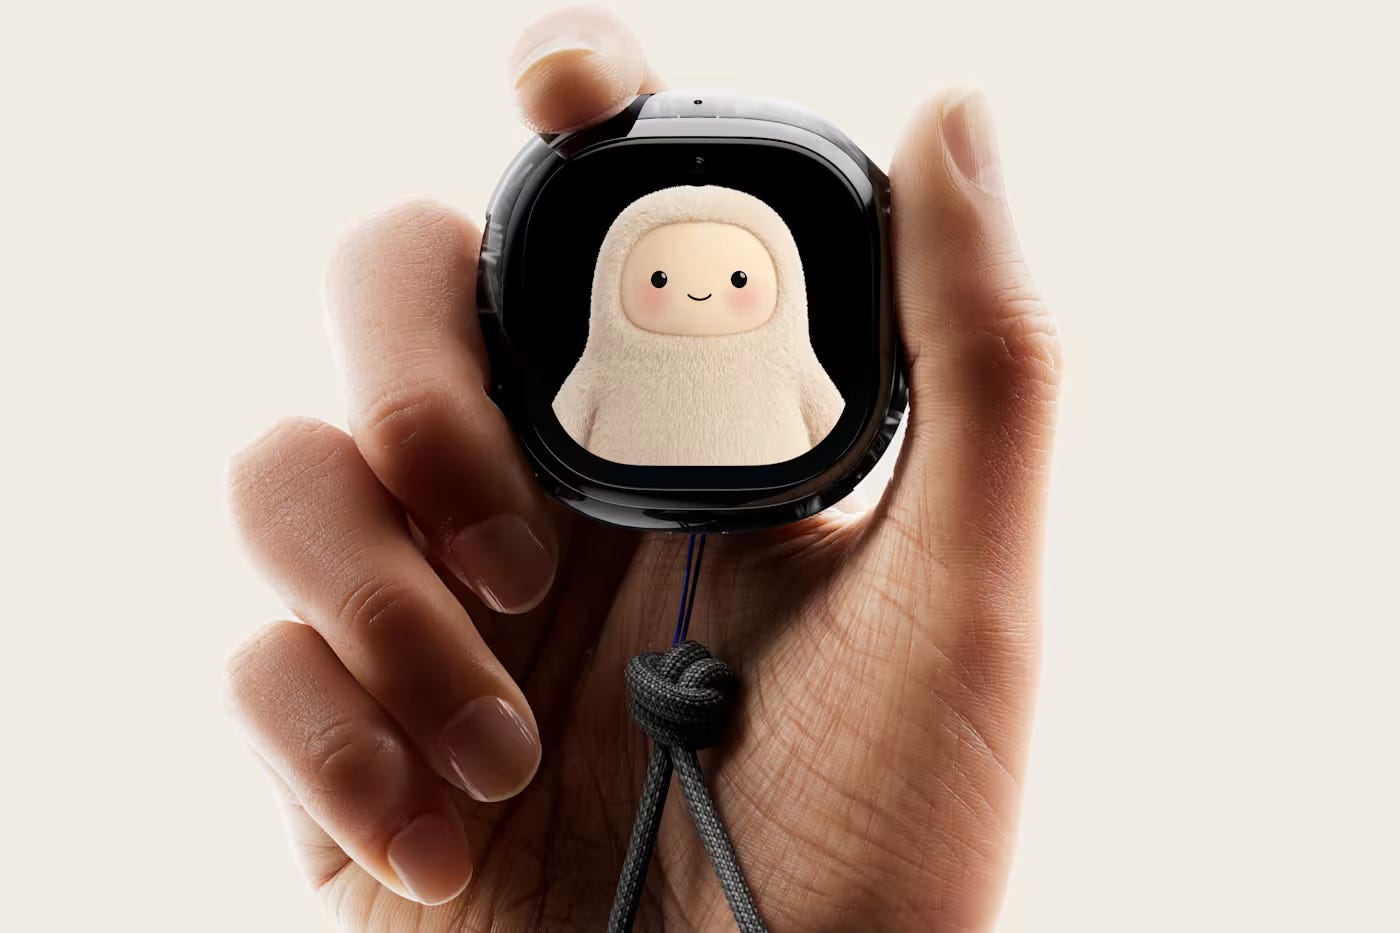
At the other end of the hardware spectrum, Meta unveiled VR glasses weighing roughly 100 grams by moving much of the compute, battery and storage into a separate puck. Apple’s Vision Pro weighs many times more. Meta’s answer is less elegant in one sense (there’s a tether) but potentially much more wearable.
The interesting part is the range of experiments. Meta is testing whether a personal AI belongs in your phone, your glasses, a VR headset, or literally hanging off your bag.
Why it matters: Meta is no longer just adding AI to its existing products. It is beginning to build an ecosystem around the idea that your AI should follow you across them.
04 — TSMC plans a dedicated validation loop for advanced packaging
TSMC is building infrastructure in Kaohsiung to speed up a less visible part of semiconductor manufacturing: qualifying new equipment before it touches production.
The company plans a modular “Mini-Loop” where suppliers can test equipment and process integrations for CoWoS, the advanced packaging technology used to combine AI accelerators with high-bandwidth memory.
The target is to make validation 25% to 50% faster.
That is a useful signal about where the semiconductor bottleneck is moving. Making an AI chip increasingly depends not just on fabricating the silicon, but on packaging multiple dies, integrating memory and qualifying an entire ecosystem of increasingly specialized equipment.
Why it matters: Scaling AI chips is becoming as much about speeding up the manufacturing system around the wafer as building more wafer capacity.
05 — Inference providers surge as frontier models get cheaper
OpenAI says GPT-6 Sol and Luna are priced 50% below their GPT-5.6 predecessors, while Anthropic says Opus 5.5 costs about 40% less to run than Opus 5 on typical workloads.
At the same time, inference providers are being valued more highly than ever. Modal is reportedly in talks at around $15 billion, roughly triple its valuation four months ago; Baseten at around $26 billion. Fireworks could target $30 billion in a new round, while Fal has discussed $15–20 billion.
The timing is interesting. Replit CEO Amjad Masad said this week that the company is probably using less open-source AI than it was in January because OpenAI has cut prices so aggressively.
That puts some pressure on the original pitch for inference providers: open models were often cheaper than the frontier labs. But demand for the infrastructure around models is still growing quickly. Fireworks says it has passed $1 billion in annualized revenue, with 95% of the tokens it serves coming from models specialized for particular customers or tasks.
ALSO
Amazon blocks Meta’s Muse shopping agent
Amazon has stopped Muse from shopping on its platform, citing unauthorized automated access and security concerns. Meta can build an agent capable of navigating the web; whether the web allows that agent to act is becoming a different problem. The Verge
AI agents are starting to solicit scientists
Researchers are beginning to receive unsolicited requests from AI agents seeking data, collaborations and paid work. One statistician interviewed by Nature discovered that an apparently normal request for research data had come from an agent rather than another researcher. Nature
Intrinsic open-sources part of its industrial-robotics stack
Alphabet’s Intrinsic released core pieces of its robotics platform as open source, including ROS-compatible services, hardware-independent real-time control and digital-twin infrastructure. Physical AI is starting to get an open software layer underneath the models. Intrinsic
AI startups (and funds) pumping and jumping
Sequoia’s Pat Grady shared an investor update saying that across seven recent Sequoia investments, the firm’s average entry valuation was $110 million; within the next round, later investors were paying an average $3.4 billion. He also shared that Typesafe reached $100M revenue (unclear if annualized) in just 7 days, after two years of building in stealth. Another Sequoia partner has recently come under fire for the “dual pricing” tactics. His response: “other investors are willing to pay a high price for a hot company at multiples above”.
In other reports, similar “momentum” rounds are appearing elsewhere, like Ineffable Intelligence reportedly jumped from roughly $55 million pre-money to $4 billion within weeks even without a product.
There may be nowhere to plug in half the GPUs
Morgan Stanley estimates U.S. data centers could need roughly 68 GW of new power through 2028. Projects already under construction and contracted grid capacity account for only about 30 GW (less than half)
Put differently: if the projected compute actually arrives, a huge share of it may not have power waiting for it. Some interesting pundits from market researchers in here.